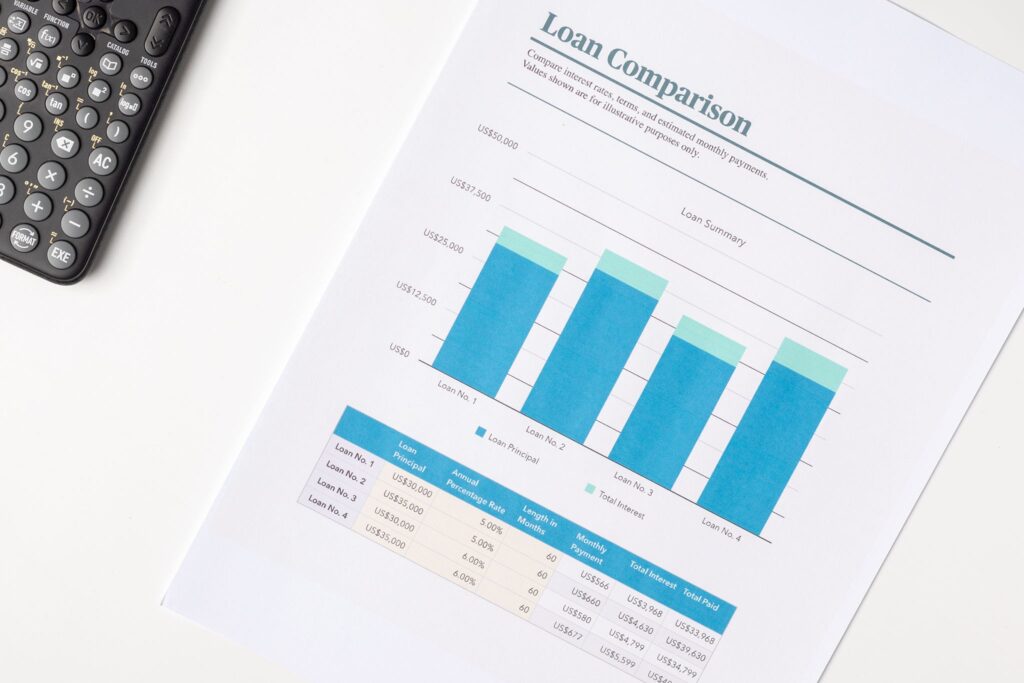

Facing heavy credit obligations, mounting penal interest, or multiple personal loan EMIs can quickly overwhelm household finances. When unexpected circumstances like job loss, business downturns, or severe medical expenses strike, standard monthly repayments become unsustainable. In such stressful moments, acting hastily—whether by taking new high-interest loans or liquidating long-term family investments—often worsens your overall financial position.
Before committing to any debt resolution path, borrowers must thoroughly evaluate their real liquid capacity, liability structure, and statutory rights. Partnering with a dedicated loan settlement expert
enables you to assess all available financial remedies, halt escalating bank penalties, and create a realistic strategy to become fully debts free
.
4 Common Debt Relief Options Compared
Evaluating your financial choices requires understanding how each resolution method affects your cash flow, total cost, and credit profile:
1. Traditional EMI Restructuring
Lenders may agree to extend your loan tenure to reduce monthly EMI payments. While this provides immediate cash flow relief, extending the repayment period significantly increases the total interest paid over the life of the loan.
2. Debt Consolidation Loans
Combining multiple credit card balances and unsecured personal loans into a single lower-interest loan can simplify payments. However, securing a consolidation loan requires a healthy credit score, which is rarely an option for borrowers already in financial distress.
3. Exhausting Emergency Reserves
Using primary family savings, retirement funds, or essential assets to pay off unsecured credit leaves your household vulnerable to basic living disruptions. Retaining a dedicated settle loan expert
helps protect essential survival reserves while addressing debt obligations.
4. Negotiated One-Time Settlement (OTS)
When regular repayment is no longer possible due to documented hardship, a structured settlement allows borrowers to pay a reduced lump sum to extinguish their debt. Working with an experienced loan settlement expert
secures significant principal discounts while waiving accrued penal fees.
5-Step Roadmap to Evaluate Your Debt Options
A systematic assessment process prevents costly mistakes and leads to long-term financial stability:
1.Step 1: Inventory All Outstanding Liabilities:Liability Audit.
Separate your original principal balances from accumulated penal interest, late fees, and auto-debit bounce charges across all bank accounts.
2.Step 2: Calculate Your True Net Disposable Surplus:Budget Protection.
Determine your essential living costs (rent, groceries, healthcare). The remaining surplus represents your real capacity for debt resolution rather than relying on unsustainable EMIs.
3.Step 3: Consult a Dedicated Settle Loan Expert:Professional Advisory.
Engage a qualified settle loan expert to evaluate your hardship documentation and redirect recovery agent communications away from your home and workplace.
4.Step 4: Negotiate a One-Time Settlement (OTS):Formal Strategy.
Your appointed loan settlement expert presents a backed hardship dossier to bank committees, securing 100% penal fee waivers and 40% to 75% principal reductions.
5.Step 5: Inspect Bank Letterhead Offers & Obtain NDC:Verification & Audit.
Thoroughly audit the written Settlement Offer Letter before making any payment. After transferring the agreed settlement sum, secure your No Dues Certificate (NDC) to ensure you are officially debts free.
Independent DIY Evaluation vs. Professional Legal Representation
Handling complex debt negotiations without expert legal backing carries significant risk compared to executing a structured resolution plan:
| Evaluation Criteria | DIY Self-Handling | Customized Strategy with a Loan Settlement Expert |
| Agent Recovery Calls | Unregulated calls causing high mental stress | Complete legal shield; all communications redirected to legal representatives |
| Penal Charge Waivers | Discretionary, minor fee adjustments (10%–20%) | 100% penal charge waiver + 50%–75% overall balance reduction |
| Cash Flow Allocation | Depletes vital emergency reserves for partial payments | Prioritizes essential household expenses while building a settlement pool |
| Hardship Presentation | Informal verbal requests often rejected by banks | Documented, legally backed hardship dossier under RBI protocols |
| Final Resolution Goal | High risk of recurring debt cycles and stress | Clear, structured pathway to becoming permanently debts free |
RBI Consumer Protection Guidelines: Under the Reserve Bank of India (RBI) Fair Practices Code, lenders and recovery agents are strictly prohibited from using abusive behavior, calling outside permitted hours (8:00 AM to 7:00 PM), or contacting unauthorized family members. Appointing a dedicatedsettle loan expert
ensures these legal protections are immediately enforced.
Take Control of Your Financial Future Today
Rushing into uncalculated debt payments or relying on high-interest digital apps only deepens financial distress. Evaluating your options thoroughly with professional guidance allows you to make informed decisions that protect your family and liquid assets.
By partnering with DebtsFree
, you gain an experienced team of financial advisers and legal resolution experts. A dedicated loan settlement expert
will audit your liabilities, shield you from recovery pressure, and negotiate a fair settlement structure tailored to your actual financial capacity.
Reclaim your peace of mind. Consult a trusted settle loan expert
now, stop mounting penalties legally, and take your first step toward becoming permanently debts free
.