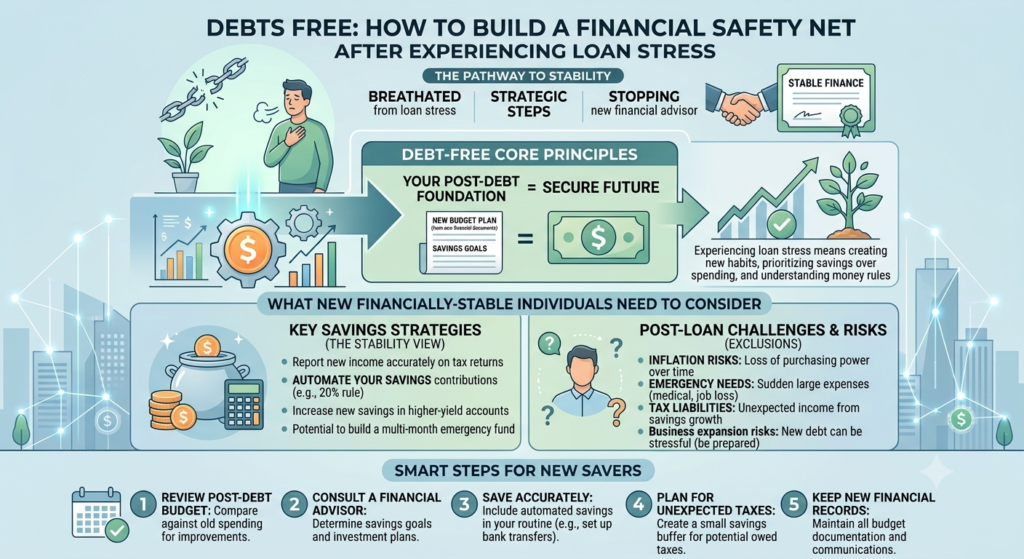

Facing severe financial distress, compounding credit card bills, and unmanageable personal loan EMIs can make any household feel completely overwhelmed. When economic shocks or sudden career disruptions impact your monthly income, keeping up with multiple debt obligations becomes an immense challenge. Whether you are juggling short-term credit lines or long-term structural liabilities, taking a proactive approach to your financial recovery is essential. Before initiating discussions for a formal loan settlement, learning how to build a robust financial safety net after experiencing loan stress is critical to achieving financial freedom and becoming completely debts free.
When working through a financial crisis, attempting to recover without setting aside emergency reserves leaves you vulnerable to repeat borrowing and chronic financial instability. Establishing a protective safety net allows you to approach a settle loan recovery phase with absolute confidence and control. Whether you are managing discussions independently or consulting a professional loan settlement strategist, mastering post-crisis cash flow management is vital. Below is an exhaustive guide on how to build your safety net and structure your path to become debts free. You can also explore foundational recovery frameworks directly on Debts Free.
1. Consolidating All Credit Data Into a Master Post-Crisis Inventory
The very first step in building your safety net is gathering every single piece of credit documentation you possess across all active and resolved lenders.
- Pulling Credit Reports: Download your latest CIBIL, Experian, and CRIF High Mark reports to get an uncompromised master list of every account registered under your PAN.
- Professional Guidance: To understand how structured recovery helps distressed borrowers become debts free, review the detailed insights available on the Debts Free Homepage. Recognizing your exact liabilities ensures you miss nothing while working toward a viable loan settlement.
2. Auditing and Categorizing Your Dues by Component
Once your liabilities are accounted for, your safety net planning must separate past settlement obligations from future liquidity requirements.
- Isolating the Core Principal: Track how much of any remaining disbursed amount requires attention, ensuring bank-levied late fees and over-limit charges are fully resolved or waived.
- Structured Frameworks: Maintaining a rigorous numerical breakdown helps you verify whether your post-recovery budget aligns with actual ledger data. Learn more about structural frameworks by visiting Debts Free About Us. You can also evaluate options to settle loan accounts effectively once your ledger is audited.
3. Calculating Your Monthly Settlement Surplus Pool and Savings Target
A financial safety net is built by intentionally redirecting cash flows that previously went toward unmanageable debt service into secure emergency reserves.
- Establishing Survival Baselines: Subtract your non-negotiable living costs (housing, groceries, and critical healthcare) from your net household income to determine your true monthly savings pool.
- Mitigating Exposure: A professional loan settlement planner meticulously scrutinizes these cash flows to help you build a centralized reserve fund. You can reach out for guidance via the Debts Free Contact Page.
4. Shifting From Minimum Payments to a Safety Net Accumulation Strategy
One of the most dangerous traps borrowers fall into is falling back on high-interest credit cards at the first sign of an unexpected expense instead of relying on a safety net.
- The Risk of Haste: Making partial, unstructured payments on low-priority credit lines using emergency cash provides zero long-term relief while reactive borrowing restarts the cycle of debt.
- Building a Centralized Reserve: Instead, use your post-settlement financial stability to channel your monthly surplus into a dedicated, high-yield emergency account. As accounts mature toward default or resolution, you can deploy this reserve to fund a formal loan settlement and move closer to being debts free.
- Strategic Progress: Keeping your records organized brings you one step closer to your goal. To explore comprehensive debt relief structures, review the services outlined on Debts Free.
5. Securing Permanent Legal Closure and NDCs While Funding Your Safety Net
Building a financial safety net does not end when your savings account grows; it requires tracking the entire lifecycle of every resolved account until final legal closure is achieved.
- Saving Digital Records: Save all email threads, scanned notices, UTR transfer numbers, and payment receipts alongside your safety net records in a secure digital folder.
- No Dues Certificate (NDC): Verify that the final written communication you receive for each resolved loan confirms a zero balance, protecting your newly built safety net from surprise claims and helping you successfully settle loan liabilities.
- Credit Report Reflection: Track your credit report post-payment to ensure every account status is updated accurately. Explore more resources via Debts Free.
Conclusion
Mastering how to build a financial safety net after experiencing loan stress is a vital step toward regaining control of your financial future. By consolidating your credit data, auditing your ledger components, calculating a monthly surplus, rejecting unviable borrowing habits, and securing formal closure certificates, you step into financial recovery from a position of absolute strength.
If managing complex documentation trails and negotiating with institutional creditors feels overwhelming, structured guidance can make all the difference. To explore tailored resolution plans, protect your rights against recovery harassment, and take confident steps toward a successful loan settlement to become completely debts free, consult trusted resources through Debts Free. Taking control of your safety net today is your safest path to long-term financial resilience.